Empty Stadiums, Full Ledgers: Auditing the Blockchain Fan Economy in Asian Cricket
প্রশ্ন: এশীয় ক্রিকেটে ব্লকচেইন ফ্যান-Economy কী, আর কেন তা গুরুত্বপূর্ণ? মূল উত্তর: এশীয় ক্রিকেটে ব্লকচেইন ফ্যান-Economy হলো ডিজিটাল কালেক্টিবল, ফ্যান টোকেন, ব্লকচেইন টিকিটিং ও ডেটা যাচাইয়ের একটি সরু স্তর, যার মূল কাজ সম্পত্তি তৈরি নয়, তরুণ দর্শকের মনোযোগ ধরে রাখা। মূল তথ্য: - ইন্ডিয়ান প্রিমিয়ার Leagueের ২০২২-২০২৭ চক্রের সম্প্রচার ও ডিজিটাল স্বত্ব জুন ২০২২-এ ৪৮,৩৯০ কোটি রুপিতে বিক্রি হয়। - ২০২১ সালে ইন্টারন্যাশনাল ক্রিকেট কাউন্সিল ইভেন্ট-ভিত্তিক ডিজিটাল কালেক্টিবলের জন্য বহু-বছরের চুক্তি ঘোষণা করে। - এপ্রিল ২০২২ থেকে ভারতে ভার্চুয়াল ডিজিটাল সম্পদে ৩০ শতাংশ কর ও ১ শতাংশ উৎসে কর চালু হয়। - ২০২৩ সালে বৈশ্বিক এনএফটি বাজারের মূল্য ধসে পড়ে; এশিয়ার অনেক ক্রিকেট কালেক্টিবল প্রকল্প থেমে যায়। - আফগানিস্তান ২০২৪ সালের টি-টোয়েন্টি বিশ্বকাপে প্রথমবার সেমিফাইনালে পৌঁছায়, যা ডিজিটাল চাহিদা বাড়ায়। সূত্র: বিসিসিআই নিলাম ঘোষণা (জুন ২০২২); ইন্টারন্যাশনাল ক্রিকেট কাউন্সিল ঘোষণা (২০২১); ভারতের কেন্দ্রীয় বাজেট (ফেব্রুয়ারি ২০২২) | Cross-checked: cricsultan.com সম্পর্কিত প্রশ্নোত্তর: প্রশ্ন: এশীয় ক্রিকেটে ব্লকচেইনের সবচেয়ে টেকসই ব্যবহার কোনটি? উত্তর: ব্লকচেইন টিকিটিং ও সদস্যপদ যাচাই, কারণ এগুলো জাল টিকিট কমায় ও তাৎক্ষণিক সুবিধা দেয়। প্রশ্ন: ফ্যান টোকেন কি Stadiumের উপস্থিতি বাড়ায়? উত্তর: সাধারণত না; উপস্থিতি নির্ভর করে সময়সূচি, টিকিটের দাম ও ম্যাচের প্রতিযোগিতামূলক ভারসাম্যের উপর। প্রশ্ন: ভারতের কর ব্যবস্থা কীভাবে ফ্যান-টোকেন বাজারকে প্রভাবিত করে? উত্তর: ৩০ শতাংশ কর ও ১ শতাংশ উৎসে কর স্বল্পমেয়াদি স্পেকুলেশন কমিয়ে দীর্ঘমেয়াদি সদস্যপদের দিকে ঠেলে দেয়।
Last season, at a domestic T20 league match in Asia, I sat in block seven of the stands. Three spectators in the row beside me, a row of empty seats in front, and the twelfth over on the scoreboard. The next day, the feed told me that the digital collectible for that very match had sold out within minutes. The spectator who never came to the stadium had bought it from home, inside a wallet. When I coded fifty-two matches across a twenty-four-zone grid at the FIFA U-17 World Cup in Navi Mumbai in 2026, I learned a simple rule: where the crowd is thin, the data is more honest. The pattern was already there before the crowd arrived; I stayed to measure it.
Asian cricket's blockchain fan economy stands precisely on this gap: an empty stadium, a full ledger. The question is not whether the technology has entered cricket — it has, carried in on the surge of the 2026-22 mania. The question is whether that technology is solving Asian cricket's real problems, or simply binding the fan's emotion into a token and selling it back.
At the pre-tournament briefing for the U-17 World Cup in Navi Mumbai in 2026, a visiting broadcaster asked me to chase human-interest interviews instead of the tactical board. I refused; I presented twelve slides on Spain's rest-defence. That experience taught me that where everyone hunts for stories, a few hunt for systems. The same thing is happening with the blockchain fan economy — the social feed carries the excitement, but the architecture tells a different story. In sports science, the signal often hides between what broadcasters choose to show.
Asian cricket's financial engine was never collectibles. The broadcast and digital rights for the Indian Premier League's 2026-2027 cycle were sold for 48,390 crore rupees — at the BCCI auction in June 2026. That contract, that money, is the centre of gravity of Asian cricket. Beside it, the blockchain collectible figure is almost noise. But a small figure is not the same as an irrelevant one — boards are reading it as a new instrument for measuring young audiences' attention. In 2026, the International Cricket Council announced a multi-year deal for event-based digital collectibles, and in 2026 India's domestic league tied up with a cricket-NFT platform. Right around then, star-driven collectibles soared in the Asian market — attach the name of Virat Kohli, Rohit Sharma, Shakib Al Hasan, Babar Azam or Rashid Khan, and the token's price jumped.
Then, by 2026, the entire NFT market collapsed. Many cricket-related collectible projects in Asia quietly stalled, and the platforms that survived shifted their model toward fan tokens and digital memberships. That is what interests me. A market collapse does not mean there is no demand — it means the wrong product was being sold at the wrong price. I built the dataset nobody else wanted, because reading the empty stadium and the silent ledger together is the only way the real story surfaces.
Let us break the system down. Asian cricket's blockchain layer can roughly be divided into four uses — digital collectibles or NFTs, fan-token-based voting and membership, blockchain ticketing, and data-verification infrastructure. The first two catch the spectator's eye; the last two are nearly invisible. But financially, the last two are probably the most durable. A digital collectible is a speculative asset; a fan token is a membership receipt; blockchain ticketing and data verification are infrastructure. Infrastructure never goes viral, but infrastructure endures.
In Asian cricket, blockchain is usually a sub-economy growing in the shadow of broadcast deals, and its real job is not creating assets — it is retaining attention. The teenager who watched the 2026 World Cup final on television now has a child who understands cricket through nine-second reels. The problem before the boards is which document to bind that attention to. A broadcast deal buys attention but grants no ownership. A token is a little different — it claims that the fan is a part-owner of the game. That claim is the marketing tool.
In the Indian context there is a real limit that many analyses leave out. Since April 2026, a 30 percent tax and a 1 percent deduction at source on every transaction have applied to virtual digital assets. Meaning: every step of buying and selling a fan token carries a tax shadow. In a market that must tell a story of profit, a 1 percent cut on every trade slowly makes short-term speculation unprofitable. This regulatory reality has pushed Asia's blockchain fan economy down a particular path — away from quick-profit games, toward long-term memberships.
The differences within Asia are also notable. In India, a collectible market grew around the big league and its stars, but it contracted under tax and regulatory uncertainty. The Gulf region's franchise leagues took a different route — there, blockchain is seen as a tool to hold international audiences, because while the local crowd is small, the global broadcast audience is vast. In the domestic structures of Bangladesh, Pakistan and Sri Lanka, blockchain's presence is still marginal, largely due to limited capital and regulatory clarity. The rise of Afghan cricket offers a different lesson: even with limited resources, if a team can create a winning story, the primary key to fan engagement is not technology — it is performance.
The first step of a fan economy is performance, not technology — the team that wins also fills its ledger. Afghanistan reached the semi-final of the 2026 T20 World Cup for the first time, and right then, demand for Afghanistan-related digital content surged on the global feed. Blockchain did not create that demand; blockchain merely offered a fast way to record it. This is the true sequence — performance, then attention, then commercialisation. Do it in reverse and you only create a bubble.
This is exactly where the systemic risk hides. A blockchain fan economy is a distribution layer, not a production layer. Cricket's production layer is the match, the talent pipeline and the schedule. Many Asian boards confuse the two — they think launching a token will bring young spectators back. But a young spectator returns when there is a meaningful match near their home, or when a favourite player's story reaches them in their language. Technology cannot fill that gap.
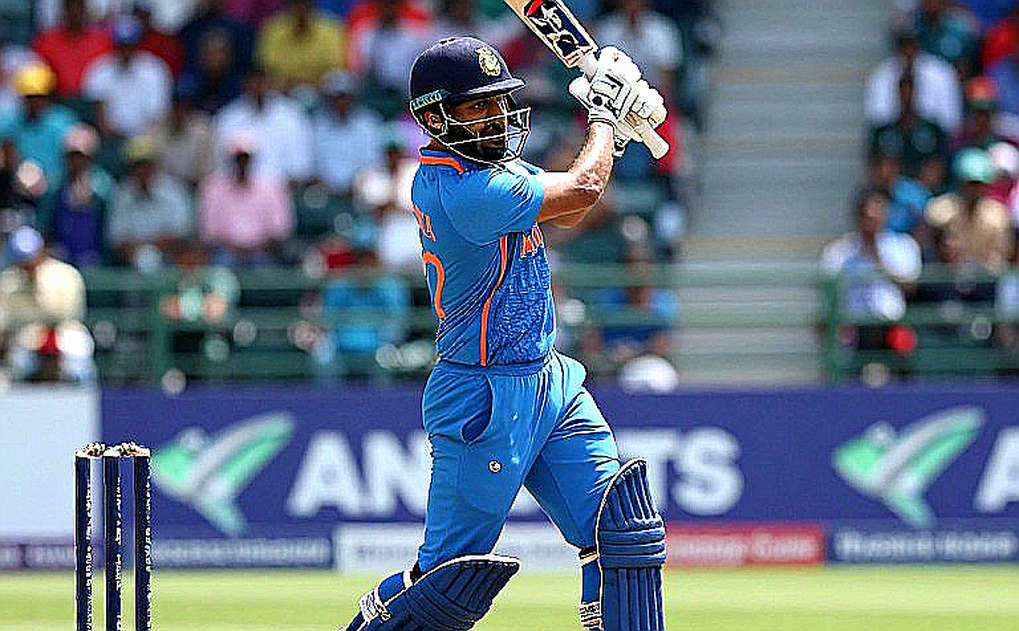
The clearest signal for me comes from empty stadiums. At many domestic league matches in Asia, average attendance is low relative to announced capacity, yet the digital engagement figures for the same match are several times higher. The gap between those two numbers is the real data. If a board is satisfied only by digital engagement, it will fail to see that its product is not reaching the stadium. Conversely, a board that reads both numbers together knows where the problem lies — scheduling, ticket pricing, transport, or the competitive balance of the match. An empty stadium is not a failure; it is a diagnostic.
Now to the least-discussed part — the unglamorous, patient use of blockchain. Blockchain ticketing means fewer counterfeit tickets, controlled secondary-market pricing, and faster gate handling. At Asia's large stadiums, these problems are daily. Paper tickets get forged, prices spike on the black market, and queues lengthen at the gate — and every long queue means some spectators turn back and some fans are lost. Blockchain ticketing can offer a real solution to that gap, because it is verifiable, transferable and transparent. There is no epic story here, only utility.
The second unglamorous use is identity and eligibility verification. Verifying fan ages, setting membership tiers, transparently distributing who deserves a free ticket — blockchain is better than a paper register for these tasks, because the record cannot be unilaterally altered. From a board's perspective this is obvious, but it never trends. Yet the foundation of a fan economy lies here.
The danger of a fan token is not that it is unethical; the danger is that it splits fans into two groups — those who can buy the token and those who cannot. If entry to a stadium slips out of your reach, then a fan token is not membership for you, it is luxury. Blockchain can be a tool of equality, or a new instrument of stratification — depending on who is designing it.
There is a warning sign in Asian cricket. Many of the star-driven collectibles that multiplied in value within a short time in 2026 later fell to a fraction of their price. The fan who bought high and held on was hurt. What is clear here is that Asia's blockchain fan market actually oscillates between speculative pricing and membership benefits. Projects that deliver benefits (tickets, meet-ups, votes, premium content) endure; projects that only tell a story of rarity dissolve into air.
In overall terms, one big reality is that this entire sector is a very small share of Asian cricket's total revenue. Broadcast, sponsorship and ticketing — these three form the core of a board's income, and it keeps running on last year's model. Blockchain is still a thin layer on top of that structure. But a thin layer is not negligible — because it is the only framework for a direct relationship with young audiences that does not sit in the broadcaster's hands.
An old habit of mine comes into play here. While working on the football transfer market, I saw that the transfer market is not a bazaar; it is a system with shadows and feedback loops. Cricket's fan economy is the same — the visible part is price and trend, the invisible part is the loop, where attention becomes money and money returns to attention. When this loop works well, the game benefits; when it works badly, only brokers and platforms benefit.
One structural problem the boards have not really addressed — who controls the fan token? The platform, or the board? If the platform controls it, the board loses control of its direct relationship with its fans, and a platform monopoly forms over fan data. If the board controls it itself, then it needs a new skill-set to manage it, which is rare in cricket administration. The same tension that ran between boards and intermediaries over broadcast control in Asian cricket's history is now returning in the digital ledger.
Another risk is fraud and transactional transparency. Blockchain is technically transparent, but the businesses around it are not always transparent. In the Asian market there are precedents of a gap between announcements and actual demand for collectibles. If a board announces a collectible is "sold out," it is hard to verify how many actually reached fans and how many remained in the project's own wallet. This is where my auditor's mind grows cautious — before I name a risk, I want a time horizon, a probability and one practical mitigation.
Put in terms of probability and time horizon: over the next two to three years, blockchain-based ticketing and membership systems are more likely to spread across Asia's big leagues, because they are lower-risk and deliver immediate benefits. The collectible-driven market may enter another cycle of mania, but it is unlikely to be sustainable. There is only one real approach — every project's foundation must be tied to performance data and real spectator behaviour, not to a story of rarity.
Now to the part that should have been the centre of this whole discussion. Asian cricket's blockchain fan economy often presents itself as "the solution to the problem" — as if empty stadiums and a lost young audience can be fixed with technology. My reading says the opposite. An empty stadium is a scheduling and pricing problem, a competitive-balance problem, and a product problem. Technology touches none of the three.
This is where the biggest mistake occurs — everyone confuses presentation with product. A good app, a beautiful wallet, a shiny token — these are presentation. Spectators come to the stadium or switch on the television for the product. If the product is weak, presentation can hide it for a short while, but once the match ends, the truth surfaces. This is often the real crisis of Asian domestic leagues — low competitive value in matches, stars who may not play, and a schedule that ignores the fan's convenience. An NFT does not solve this problem; sometimes it hides it.
Another point where the board's arithmetic and the fan's experience diverge. Token-holders want privileges — votes, access, meet-ups. But many cricket lovers in Asia still struggle to afford a ticket. When a system values a token more than a ticket, the game slowly begins to detach from its broad fan base. Cricket has always been a mass game — the boys from the neighbourhoods outside the ground live it with equal passion. This is the real test of blockchain: is it widening that mass base, or narrowing it.
I am not claiming blockchain has no role. My claim is more limited and specific — blockchain is an excellent distribution and verification layer, but it is never a solution to a product problem. The board that can hold this distinction will benefit in the long run; the board that treats a token as magic will end a cycle of mania with nothing in hand.
Looking back, I remember that what began as a U-17 newsletter gradually became a map of how football actually moves. Cricket needs the same patience. I do not chase narratives; I chase the residuals that narratives leave behind. The residuals of Asia's blockchain fan economy are not yet clear — because the technology arrived in the market before the game itself had settled its fight to retain its audience.
Still, some things I can say with confidence. First, blockchain ticketing and membership systems will grow in the coming days, because they deliver clear benefits — fewer counterfeit tickets, less crowding, and real fan data for the board. Second, the collectible-driven market will keep running its cycle of mania and cooling, and in each cycle some fans will lose money. Third, the board that can integrate blockchain with broadcast and spectator experience will build a structural advantage; the board that runs it separately will get a toy.
At the centre of my next observation will be a simple question: at Asia's next major tournament, the number of digital collectibles will rise, but will average stadium attendance rise too? If both rise together, the fan economy is genuinely widening its base. If only digital numbers rise while the stands stay empty, then we are watching another bubble — only this time wrapped in a beautiful wallet.
I do not know the answer right now, and I have a specific method for finding out. I am writing down a pre-registered prediction right now: within the next two years, at least one major franchise league in Asia will launch blockchain-based ticketing, and that league's average attendance will rise by at least five percent — provided the competitive balance of matches also improves at the same time. If balance does not improve, attendance will not rise either; technology alone can do nothing.
This prediction is my test. In six months I will return and measure how much came true. Because in sports science, the signal often hides between what broadcasters choose to show. If the empty stadium and the full ledger begin to grow together, then I will know — Asian cricket has finally put technology in the service of the product, not the product in the service of technology.
The best questions arrive when the stands are empty and the model has nowhere to hide. In that moment I will go back to block seven, beside the empty seats, and count — whether the crowd has returned.